All Categories
Featured


Common FAQs Regarding 2026 Medi-Cal Coverage
Table of Contents
If you get a number that is 0 or less, then you have no share of expense. You just have to pay a share of expense in months when you have medical expenditures. Example You live alone and have $1,935 per month in countable income and have no other insurance coverage.
You receive ABD-MN Medi-Cal. Your share of expense is $1,935 (your countable income) - $600 (the Upkeep Requirements Level for an individual living alone) = $1,335. You will have to pay the first $1,335 in medical expenses during the month before Medi-Cal will begin covering you. If you get Supplemental Security Income (SSI), a benefit for people with low earnings who are aged, blind, or disabled, you get Medi-Cal immediately.
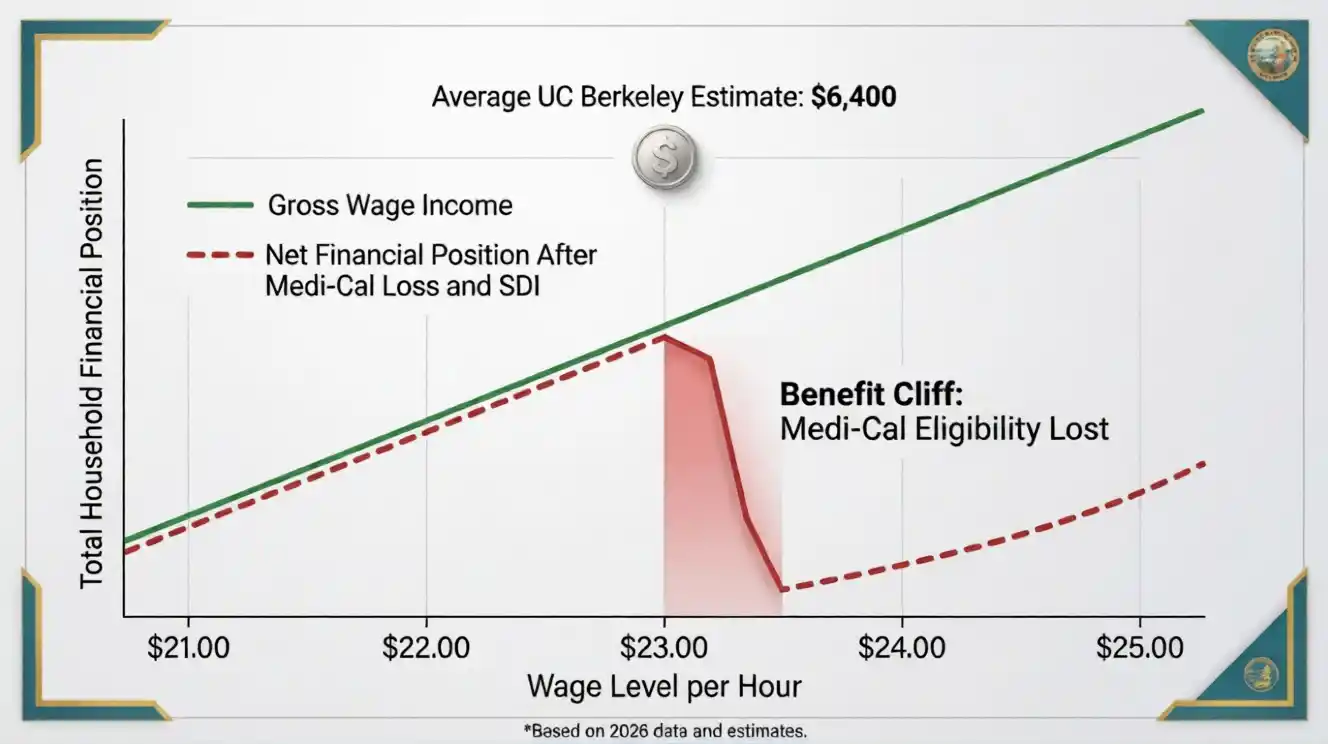
Check out DB101's SSI short article for more details about whether you qualify for SSI. If your SSI advantages go to zero because you return to work, an SSI rule called 1619(b) lets you to keep your Medi-Cal coverage if you: Were eligible for SSI benefits for at least 1 month Required Medi-Cal protection to keep working Still meet all the other SSI requirements, such as being disabled, having resources listed below $2,000, and Make less than $66,078 in gross income annually. After he began working, his earnings increased to $2,800 per month ($33,600 every year) triggering his regular monthly SSI advantage to drop to no. Although his income is now greater than the typical earnings limits for Medi-Cal, he is still qualified for Medi-Cal through 1619(b) due to the fact that his yearly earnings is less than $66,078.
Harmony SoCal Insurance Services ReviewsLocal Advice On CA Life Coverage
If you are working, handicapped, and your earnings is too high to certify for free Medi-Cal, Medi-Cal's Working Handicapped Program might enable you to get Medi-Cal. Medi-Cal's Working Handicapped Program utilized to have a regular monthly premium.
You don't have to meet the income and work requirements. Be working and making income. The Medi-Cal guidelines do not define what "working" means for this program, and you can qualify if you are working part time.
Have resources at or listed below the limitation ($130,000 for people; $195,000 for couples). For this program, there are a couple of extra types of resources that are not counted: Retirement funds like 401(k)'s are not counted as resources. Any money that you make from your work while you are on the program will not be counted as resources, as long as you put that cash into a separate bank account.
Steps to Apply for California Coverage
Find out more about ABLE accounts on DB101. Have countable income less than 250% of the Federal Hardship Level ($3,325 monthly for individuals and $4,508 for couples). Remember that these are countable income limits, which is your gross earnings minus specific reductions. Your gross earnings can be much greater than your countable income.
Special needs earnings does not count for the WDP program. This suggests that SSDI, Employee's Settlement, California State Special Needs Insurance Coverage, and any federal, state, or private impairment benefits are not thought about as income for this program. Keep in mind: If you got SSDI before you reached retirement age and now your SSDI advantages have been converted to Social Security retirement advantages, they will not be counted as earnings either.
Again, disability income does not count. If you are single and reside on your own, you can utilize the tool listed below to help determine your countable earnings. Remember not to note any money you obtain from impairment advantages as unearned earnings. Compare the outcomes to the WDP earnings limitation ($3,325 each month for people) to see if you're qualified.
How to Apply for California Coverage
Medi-Cal Eligibility Categories Summary Low to moderate income 138% of FPL for adults 19-64 years old. Made and unearned income is counted based on Internal revenue service rules for modified adjusted gross earnings (MAGI).

Latest Posts

Navigating 2026 Medi-Cal Guidelines
Does Your Family Be Eligible for 2026 Medi-Cal
Your Guide to Medi-Cal Coverage in SoCal